When an employee joins, most employers know to file Form CP22. But when an employee leaves — resigns, is terminated, retires, or passes away — there’s an equally important tax form many forget: Form CP22A. Miss it, or pay out the employee’s final money too early, and you could be personally liable for their unpaid tax. Here’s what CP22A is, when to file it, and the retention rule that trips employers up.
What Is Form CP22A?
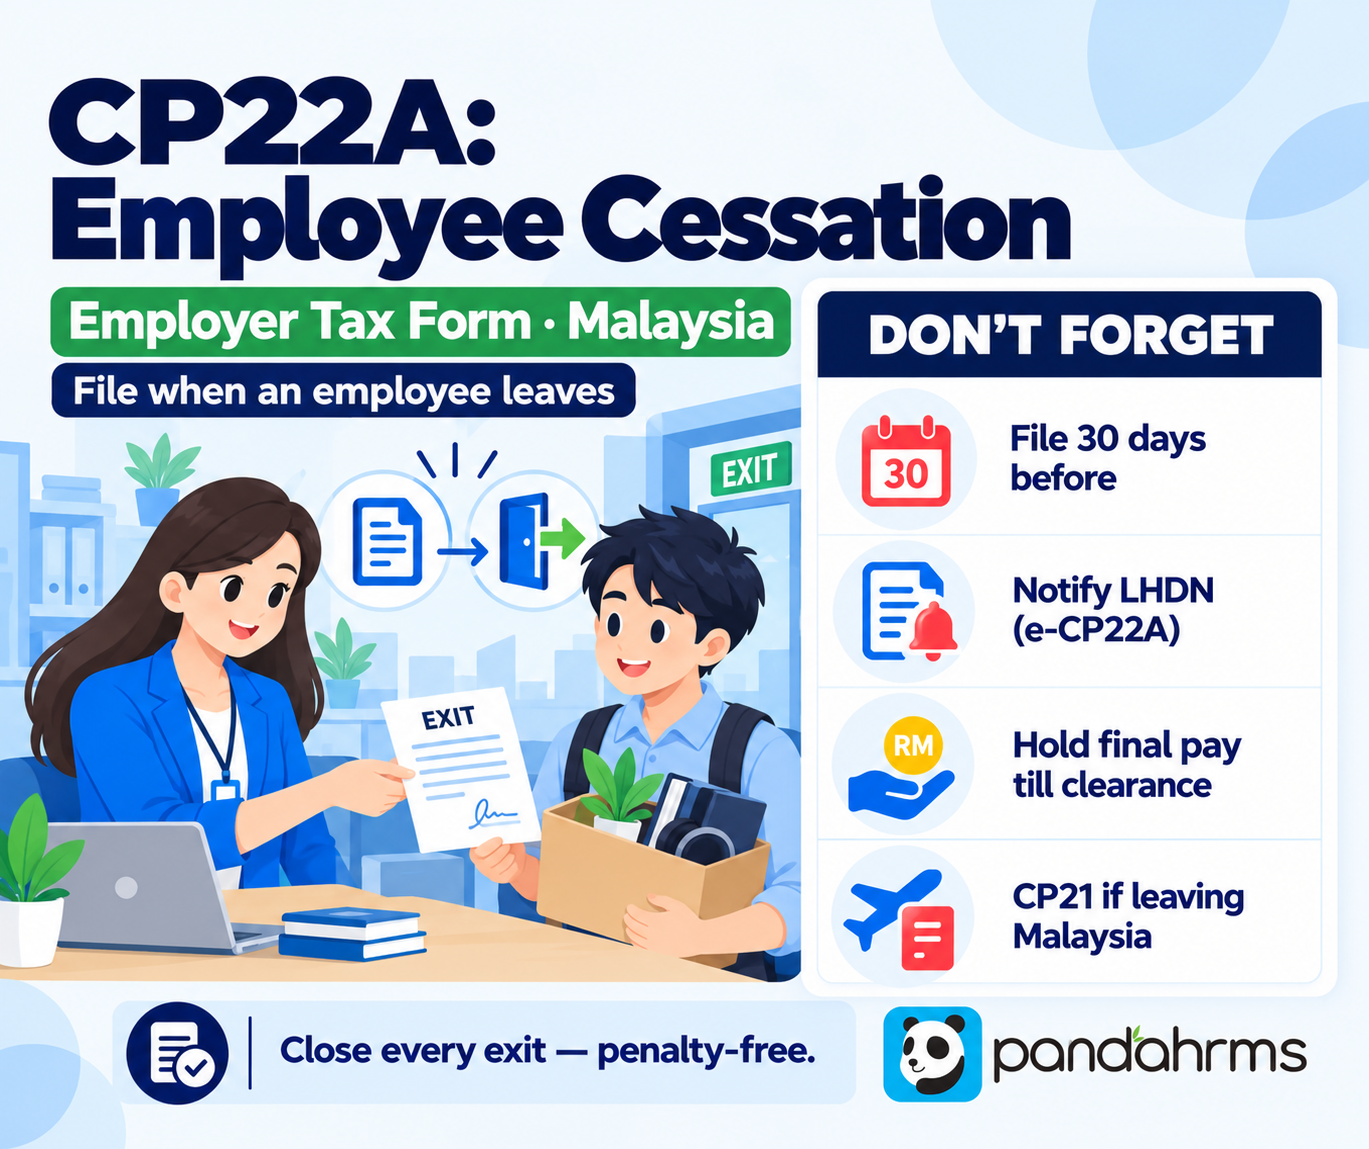
Form CP22A is the Notification of Cessation of Employment that a private-sector employer must submit to LHDN (the Inland Revenue Board) when an employee stops working. It tells LHDN the employee is leaving, so the tax authority can check whether any tax is still owed before the employee’s final pay is released.
CP22 vs CP22A vs CP21 — Don’t Mix Them Up
| Form | When it’s used |
|---|---|
| CP22 | A new employee joins. (See our CP22 guide.) |
| CP22A | An employee ceases employment in Malaysia (resign, terminate, retire, or death). |
| CP21 | An employee is leaving Malaysia for more than 3 months. |
When Must You File CP22A?
The general rule under the Income Tax Act 1967:
- At least 30 days before the employee’s cessation date, where the departure is known in advance (resignation, termination, retirement).
- Within 30 days after being informed, in the case of an employee’s death.
In practice, file it as soon as the cessation is confirmed — don’t leave it to the last day.
The Rule That Catches Employers: Money Retention
This is the part most employers miss. Once an employee ceases, the employer generally must withhold any money payable to them — final salary, unused annual leave, and so on — until the earlier of:
- 90 days after LHDN receives the CP22A, or
- LHDN issues tax clearance (Surat Penyelesaian Cukai / SPC).
The idea is to make sure any outstanding tax is settled first. Pay out everything on the last day and then find the employee owes tax, and the employer can be held liable for it. So: notify, retain, and release only once you have clearance (or the 90 days have passed).
How to Submit CP22A
CP22A is submitted electronically (e-CP22A) through the LHDN MyTax portal. Have the employee’s details, cessation date and reason, and final remuneration figures ready. Keep the acknowledgement for your records alongside their EA Form and other payroll documents.
Common Mistakes
- Forgetting CP22A entirely — treating offboarding as “just pay the final salary.”
- Missing the 30-day deadline before cessation.
- Releasing the final pay immediately instead of retaining it until clearance.
- Using CP22A when the employee is leaving the country (that needs CP21).
- Not keeping the submission acknowledgement on file.
Missing these obligations can attract penalties under the Income Tax Act — see our guide on payroll deadlines & penalties.
Where Pandahrms Helps
Offboarding is where small compliance steps get lost in the rush. Pandahrms keeps each leaver’s record — cessation date, reason, and final pay components — in one place, so the figures you need for CP22A are ready, and the final settlement (unused leave, prorated salary, statutory) is calculated correctly. With a clean, documented offboarding trail, filing CP22A on time and holding the right amount becomes a simple, repeatable step instead of a scramble.
Final Thoughts
CP22A is a small form with real consequences. Whenever an employee leaves, notify LHDN at least 30 days ahead, retain their final money until you have tax clearance, and use CP21 instead if they’re leaving the country. Build it into your offboarding checklist, and you’ll close every exit cleanly — no penalties, no personal liability for someone else’s tax.
Frequently Asked Questions (FAQs)
- What is Form CP22A used for?
It notifies LHDN that an employee has ceased (or is about to cease) employment in Malaysia, so the authority can settle any outstanding tax before the final pay is released. - When must CP22A be submitted?
At least 30 days before the employee’s cessation date where it’s known in advance, or within 30 days after being informed in the case of death. - What is the difference between CP22A and CP21?
CP22A is for an employee ceasing employment in Malaysia; CP21 is for an employee leaving Malaysia for more than three months. - Do I have to withhold the employee’s final pay?
Generally yes — the employer withholds monies due until 90 days after LHDN receives the CP22A, or until tax clearance (SPC) is issued, whichever is earlier. - How do I submit CP22A?
Electronically as e-CP22A through the LHDN MyTax portal, with the employee’s cessation details and final remuneration figures.